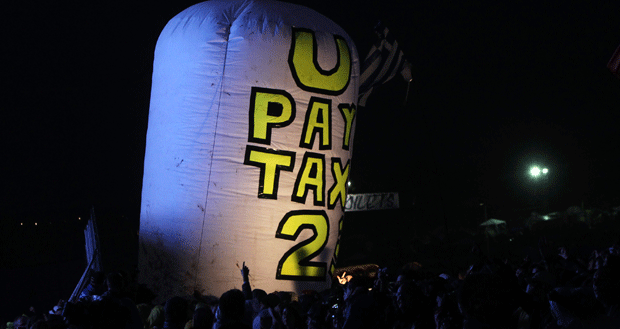Thursday, April 19, 2012

Call for papers: Political Economy of Offshore

TJN links to what this very interesting conference, to be held in Linz, Austria in November:  The Political Economy of Offshore Jurisdictions (Die Politische Ökonomie von Steuer-und Regulierungsoasen).  From the description:
"Understanding actual capitalism needs an understanding of the domain of the offshore economy, especially of tax havens and regulation-free zones. They are based at offshore jurisdictions which provide mandatory secrecy. An extensive part of the global economy is therefore able to operate in the shadows. 
...The conference will aim to highlight aspects of how offshore jurisdictions function and their impact on the global economy, for example:

  •  Business models and instruments of offshore activities;

  • The significance of the offshore economy for the current crises;
  • The role of economic theories and economists in justifying the offshore economy;
  • The role and structure of user groups and intermediaries and their strategies and tactics;
  • The history of offshore states;
  • The political systems of offshore states;
  • Current regulation discourses with respect to the offshore economy;
  • Consequences of the offshore economy for non-financial companies and different citizens of offshore jurisdictions.
The aim of this conference is to bring together researchers from different fields (such as economists, sociologists, historians and political scientists) to explore neglected aspects of the global offshore economy.
Abstracts are due September 1st, and the conference will be held in English and German.  More info at the link.  


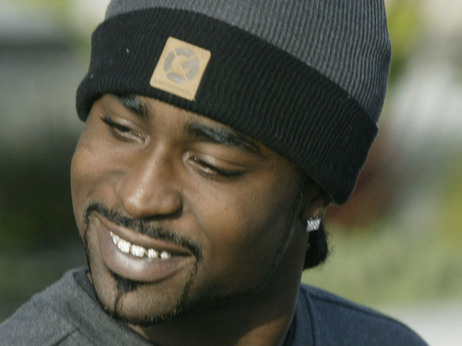
Young Buck's Tax Problem


I sent this NPR story to my tax students to both demonstrate that what they are learning has real world relevance and to remind them that they know why Young Buck can't deduct the cost of his watches.
Even though they are quite the watches (many NSFW).


From the story:
"When IRS agents raided the house of rapper Young Buck, they seized all his things: his white leather dining chairs, his watches, his craps table, his tattoo kit. Even his refrigerator. The Nashville artist, who was once part of 50 Cent's G-Unit, owed hundreds of thousands of dollars in back taxes.
... if you're an entertainer, what qualifies as a business expense can seem really murky. Your whole lifestyle is not tax deductible.   Madison has tried to deduct watches, arguing that it's a necessary business expense for his client to have a certain look. The CPAs at his company threw it back."

Ivan Rodriguez retirement, yes, there's a tax angle

I love this website where you can see the tax consequences of baseball player salaries, with and without the expiry of the Bush tax cuts, plus what the player would have paid under Eisenhower.  However it looks like Pudge's bottom line is 0 this year, clearly not the case; judging from last year he should have at least a million or so to work with.  But check out the other Rodriguez.  Without Bush, he would have paid about a million more in taxes; under Eisenhower, more than $16 million more!

Is India not entitled to tax sovereignty?

Apparently not, according to the US business lobbying industry.  They're putting pressur on Tim Geithner to put pressure on India as it contemplates enacting that controversial post-Vodafone legislation.  As the FT reports today:
A coalition of large American trade associations – mainly from the technology and financial services sectors – sent a letter to Mr Geithner asking him to “raise concerns” about the tax bill in talks with Indian officials during the spring meetings of the World Bank and International Monetary Fund this week.
...The US Treasury declined to comment on the letter to Mr Geithner. He is slated to meet Pranab Mukherjee, the Indian finance minister, this week on the sidelines of the IMF and World Bank gatherings. Pressure from the US lobbying groups will raise the odds that he will press the matter. 
...The pressure on Mr Geithner comes after George Osborne, UK chancellor, made a public intervention on the matter earlier this month on a trip to New Delhi, chastising the Indian government for its proposed changes and warning of potentially harmful effects on trade and investment. 
So now we see how "tax sovereignty" actually works out in practice.   I've long argued that there is no theoretical or empirical basis for the claim that taxation is intrinsically associated with sovereign status, and that the "soft law" nature of international taxation--enforced coordination to standards developed by powerful players through modeling and peer pressure--demonstrates that tax sovereignty isn't minded at all in practice.  This latest move against India's assertion of its sovereign taxing power is further proof.  Who is responsible for all this pressure?

I don't think these folks want to "raise concerns."  I think they want to stop India's democratically elected government from enacting legislation in accordance with its sovereign status as an independent nation, and I find it amazing that they fully expect the U.S. government to help them do that.

This is because of course if businesses really don't like what India is doing, they have a perfectly viable option, which is to do what they say they are going to do, namely, take their assets and go home.  But they do not want to do that.  They want to be able to continue doing business in India at the lowest possible cost to them, and if the Indian government won't play along and give them the tax system they want, these business leaders would like to turn this into a government-to-government conflict so that it is India against the U.S. instead of India minding its own business, writing its own laws, and opening itself to businesses willing to work within its sovereign territory according to its own rules.

Anyone is free to disagree with India's tax policy direction, and anyone is free to express "concerns" about it.  But India's decision belongs to India's people, and it is shameful to see the U.S. business lobby so brazenly insisting on their right to intervene.


Wednesday, April 18, 2012

Canada's Mutual Agreement Program

Just like its equivalent in the US, the Canada Revenue Agency seems to have begun to publish annual statistics on its mutual agreement program--the treaty-based diplomatic regime under which the government agrees on revenue allocations with other governments--only after a long information disclosure battle.  In Canada, the credit for transparency in the MAP program goes to David Sherman, who spent six years in the Courts only to eventually pry the most meager amount of information out of the CRA.

But Mr. Sherman's battle seems to have been productive for the rest of us: now we have a series of annual reports being published by the CRA, and generally with more information than that available in the IRS counterpart, which of course we can't even find.  Yes, that's another difference compared to the IRS counterpart: these statistics are actually available online, and not just to big four accounting firms.

However, I've not yet found a place where they are compiled together nicely with links; instead, I've had to google search them.  So, for David Sherman and for all of us benefitting from his hard work on transparency in the tax system, here they are:

First Report--2001-2004
2004-2005
2005-2006
2006-2007
2007-2008
2008-2009
2009-2010
2010-2011 

Notice that the first report was issued in 2005 and covered 2001-2004 only; Mr. Sherman's initial lawsuit sought information for 1995 through 1998, and he made a subsequent request for information from 1999-2004.  The information exists but the CRA just hasn't bothered to compile it.  That's too bad.  But on the other hand the CRA is light years ahead of the IRS on this.

Addendum: David Sherman advises me that his lawsuit sought disclosure of CRA to USA requests in connection with the assistance in collection provisions of the tax treaty, and not in connection with taxpayer-initiated competent authority actions; only the latter are disclosed in these MAP reports, and the CRA has refused to disclose collection assistance data on grounds such disclosure could be "injurious" to the CRAs relationship with the USA.   The CRA hasn't said why publishing such data would be injurious.  CRA still doing better with transparency than US but clearly there is plenty of room for improvement.

Why Does E&Y Get Inside Info from the IRS? A Mini-Mystery for Your Consideration.

I do a lot of research on tax treaties, tax treaty information exchange, and especially competent authority negotiations under the mutual agreement procedure (MAP)--i.e., the technical means by which countries allocate tax revenues amongst themselves.   Don't stop reading, this is an interesting story, I promise.

One of the things I study about what the competent authorities are doing under MAP is just how secretive the whole structure is.  It seems like it took a Tax Analysts FOIA battle to get the IRS to start releasing even the most basic of data on its competent authority program, and then it's only done so in aggregate statistical form.  If you want to know why I think its important that we know what it is the competent authorities are doing and why the IRS ought to be telling us at least a little bit about this program, you can read my forthcoming article called How Nations Share, here is a draft.

But this is not about those ideas.  Instead, this is about an annoying occurrence that has now come up two years in a row with respect to IRS information dissemination about the competent authority/MAP Program.  This is what happened:

I was searching around online looking for anything to do with competent authority cases, and came across this little newsletter by Ernst & Young, dated January 21, 2010.  Interesting!  It tells me that the IRS just released the "2009 Competent Authority Statistics Report on 15 January 2010," and then it describes the report, complete with a number of charts, graphs, etc.  This is a fascinating secondary source but of course within two seconds of realizing what it was about, I wanted to see the primary source.  I check the E&Y document but there is, annoyingly, no helpful ink, not even a spelled out URL, nothing but the name of the report and its purported release date.  So I google, and dig around, and google some more, and try everything I can come up with to find this elusive 2009 report.  And where is it?

No where.  No where at all.

Yet E&Y must have it, so how can this be?  I asked my local rock star law librarian for help and she made inquiries to the IRS.  Finally, at least a month later, my librarian comes back to me with an email direct from the IRS, with an attachment--a Word document showing those statistics E&Y used, accompanied by the statement "I believe you requested this information.  Let me know if it is not what you wanted."  it is!  Thank you, IRS!  But...

Huh.

OK, that's odd, I thought.  Why would the IRS go to all the trouble of putting together these statistics, and not release them to the public, like in a press release, such as on the IRS website, for example, at the IRS newsroom?  Further, if this document isn't released to the public, then how come E&Y has it, and has it in time to produce a nice glossy pamphlet (ok, it's an online pdf but my screen makes it look glossy) on the topic within six days of its purported "release"?

I dismissed my thoughts about inner circles, agency capture, conspiracies, and the tax elite, in order to get on with the business of analyzing the data.

Now I am starting to think that the "release" IS the story.

Because here, a year later, is again a very nice E&Y document, dated January 19, 2012, that looks very much like last year's.  E&Y may be going a bit slower--this time the report has been issed almost month after the purported "release" of the latest competent authority statistics, on December 16, 2011.

And again the actual report is nowhere to be found.


Why is this?   I've again asked my librarian to investigate, but what on earth is going on here.  What possible purpose could be served by "releasing" data but only actually furnishing it to E&Y?  Actually, it seems KPMG might have got their hands on it this year, as well, but didn't bother with it too much.

Any thoughts on the elusive competent authority report?   And if you have a copy of the report, can you send it to me?

And while we're on the subject, just exactly how long has the IRS been compiling and not-releasing competent authority statistics?

Addendum: Since at least 1994, by releasing only by "press drops," and it is maddening to say the least to get any kind of complete dataset.  More to come on this subject.


Tuesday, April 17, 2012

Military spending: USA vs rest of the world


From Stockholm International Peace Research Institute, latest military expenditure data.  But note that the USA isn't even in the top twenty in terms of per capita spending--that honor goes to the Middle East.

Intuit lobbying and the tax prep market

Matt Stoller suspects that Intuit's $9 million lobbying budget is spent in the pursuit of making it harder for people to file their own taxes.  No doubt about it.  He rightfully brings up Ready Return, a program I've mentioned before.

He includes this handy chart of annual lobbying by Intuit:

But even better, he has this from Intuit's annual disclosure:

“Our consumer tax business also faces significant competition from the public sectorwhere we face the risk of federal and state taxing authorities developing software or other systems to facilitate tax return preparation and electronic filing at no charge to taxpayers.  These or similar programs may be introduced or expanded in the future, which may cause us to lose customers and revenue. For example, during tax season 2010, the federal government introduced a prepaid debit card program to facilitate the refund process. Our consumer and professional tax businesses provide this service as well." 
As we well know, regulation is good for monopolies and lobbying pays off handsomely to everyone involved, but has high social costs.  


Happy Anniversary to the Canadian Charter of Rights & Freedoms

Enacted April 17, 1982, 30 years old today.  The Charter proves to be Canada's gift to world, according to a couple of American constitutional scholars.  And here it is.


Monday, April 16, 2012

Paying Taxes Makes You Feel Good

Well, or perhaps satisfied with your contribution to the greater good.  Miller McCune reports

“Economists generally assume that human beings get ‘zero utility’ from paying taxes,” lead author Iwan Djanali, who co-authored the study with his adviser, Daimen Sheehan-Connor,  said in an interview. “Zero utility is econ-speak for, ‘You get no benefit out of it.’ Obviously, consumption gives you a lot of utility. If you buy an apple, it satisfies your hunger.
“We believe that paying taxes also gives you some utility, even though you’re enjoying less consumption. You get some ‘soft utility’ out of it. We call this ‘the warm glow.’ You feel good about helping others, even though you don’t get a direct monetary reward out of it.”
The conclusions are drawn from an experiment in which some groups were paid a flat amount to do a task, and the others a net amount which yielded the same after tax as the first group.


The standard economic model would predict they’d work equally hard in both conditions, since the amount of money they walked away with was the same. Instead, they worked “significantly more in the presence of tax,” the researchers report.
This effect showed up across the board, but much more strongly in students whose major was something other than economics. “Economics majors apparently perceived less utility from paying taxes, which makes sense,” Djanali said. “In Econ 101, you’re taught you get zero utility from paying taxes. It’s ingrained in their behavior.”
The researchers "primed" the second group by reminding them what their taxes paid for (public service, infrastructure).  The researchers come to another conclusion that seems counter-intuitive:


Some economists suggest making taxes less visible, “so the impact on your behavior is less drastic,” Djanali noted. That argument favors value-added taxes, which are incorporated into the price of an item and thus less apparent to the consumer.
“Our findings suggest that [to the contrary] it might be better to make taxes more visible – to make it really clear what people are paying for,” Djanali said.
That's the goal of earmarking, as in the social security tax.

Bank of NY Wants IRS to bless its STARS

ProPublica reports on the Bank of New York foreign tax credit scheme called STARS (structured trust advantaged repackaged securities).  This is a Barclays creation and a $900 million dispute that will generate bad publicity for the IRS if it loses, and bad publicity for the bank, maybe either way.  From the report:
At issue is whether STARS was set up primarily to generate artificial foreign-tax credits, as the IRS contends; or was a legal way for BNY to obtain financing at rock-bottom rates.  The arguments heard this week will pose a crucial test of the U.S. government's resolve to rein in sophisticated corporate tax planning that has sapped vast amounts of potential revenue. Tax authorities worldwide, notably in the U.S. and U.K., are under mounting pressure to show that large companies are shouldering their share of the tax burden as part of a broader political debate about fairness and corporate social responsibility.
An investigation last year by the Financial Times and ProPublica first detailed how STARS produced tax benefits for U.S. banks beginning in 1999. In all, six banks — BNY (now Bank of New York Mellon), BB&T, Sovereign (now a unit of Santander), Wachovia (now part of Wells Fargo), Washington Mutual and Wells Fargo — participated in STARS deals with Barclays between 1999 and 2006.
...BNY has argued that the deal was a complex but entirely legal, allowing the bank access to low-cost financing from Barclays for its everyday business activities.
In the coming weeks, U.S. Tax Court will hear from the bankers, lawyers and accountants involved as well as a raft of experts. A final decision is not expected for at least several months.
With much at stake, BNY and the IRS appear to be digging in for a protracted battle. In its latest filing, BNY accuses the government of using "emotionally laden" arguments to try to deliver a "sweet sound bite." The IRS says "no rational person" would have participated in STARS if not for the foreign tax credits.
The authors conclude: "Let the war of words begin."  That about sums it up.  Will BNY do a better job than the Poriskys of the world?   

US: leading the OECD in low-wage workers

John Schmitt has a new paper entitled "Low Wage Lessons" [pdf] in which he says ": The United States is a Poor Model for Combating Low-wage Work," as illustrated by this chart:


"The United States has the highest share of low-wage work in the OECD countries analyzed here.  Moreover, the incidence of low-wage work in the United States has been rising for at least three decades, from just over 20 percent in 1979 to just under 30 percent in 2010."
Schmitt thinks the reason is the minimum wage level is too low and the EITC isn't structured properly.  He says "the EITC and minimum wage in the United States have been set too low to limit the
incidence of low pay, and the minimum wage has been set too low to prevent employers from
reaping windfalls from the eligibility structure of the EITC."  He continues with the observation that the low wages themselves are "among the least of the problems facing low wage workers':

"U.S. labor law offers workers remarkably few protections. U.S. workers, for example, have the lowest level of employment security in the OECD and no legal right to paid vacations, paid sick days, or paid parental leave.  The low level of union coverage in the United States means that contractual obligations generally don’t make up for the lack of legal guarantees. 
In the absence of legal or contractual rights, low-wage workers are the least likely to have access to core benefits. ... probably the most critical problem facing low-wage workers is the lack of access  to health care.  Rho and Schmitt estimate that in 2008, more than half (54 percent) of workers in the bottom wage quintile did not have employer-provided health insurance and more than one-third (37 percent) had no health insurance of any kind, private or public. 
The 37 percent non-coverage rate for the bottom quintile of wage earners in 2008 was up from 15 percent in 1979.


Tim Taylor comments
"Define 'low-wage jobs' as those that involve earning two-thirds or less of the median hourly wage: that is, those earning less than about $10/hour. As Schmitt notes: 'If low-wage work were a short-term state that helped connect labor-market entrants or re-entrants to longer-term, well-paid employment, high shares of low-wage work would be less of a social concern. Indeed, if low-wage work facilitated transitions from unemployment to well-paid jobs, countries might want to encourage the creation of a low-wage sector to improve workers’ welfare in the long term.' On the other side, if low-wage jobs are a near-permanent state of affairs for a substantial group of workers, or if such jobs even send a negative signal to potential future employers that this worker is going to have low productivity, then the prevalence of low-wage jobs may be of real policy concern."

In other words, he's saying that if low wage work is a stepping stone to a better future, then no worries, but in the U.S., it's generally not.  This ties in to ideas about social mobility in the US, ideas that are enduring yet mostly not borne out by the evidence; ideas that seem to explain the tendency of lower wage workers to vote against their economic self-interest in the U.S.

Taylor concludes "If we wish to build a society and an economy on rewarding work, it is a harsh fact of U.S. labor markets that such a reward is currently not apparent for many."


Clement Attlee on charity

"Charity is a cold grey loveless thing. If a rich man wants to help the poor, he should pay his taxes gladly, not dole out money at a whim."
Richard Murphy gives us this quote from Clement Attlee (1920) and says "In very many ways nothing has changed since then."  I agree.  It is always a point of contention for me when people laud the Gates and Bono's of the world, most especially when we too often discover that these philanthropists spent an awful lot of time and effort to avoid paying taxes on much of the fortune they are now spending on projects that bear their names in large and bold print.  That's why the protesters floated this balloon, and I wish they would float it more often:


You could float that balloon in the direction of a lot of people, I think, and you wouldn't be wrong in wondering why we should celebrate, for example, the naming of a research center after a particular individual when it's clear other taxpayers subsidized it by picking up the slack.

Addendum: a letter on the subject in the Guardian, also linked to by Murphy.


Two Tax Conferences of Note

My good friend John Prebble alerts me to two upcoming conferences of interest, one in the States and the other in Australia.  First, he recently issued a call for papers for the Victoria-Cornell Colloquium on Jurisprudential Perspectives of Taxation Law, which will be held at Cornell on Sept. 24-25 (You might like to work this in if you already planning on going to IFA Boston, to be held Sept. 30-Oct 4).   Prof. Prebble and Brad Wendel are co-convening the colloquium, and they are particularly keen to hear from authors interested in applying either or both coherence theory (such as the writing of Ken Kress) and the work of Ludwig Wittgenstein to the analysis of judicial reasoning in leading tax cases.   Heady stuff!  The conference abstract looks fascinating:
"The colloquium will focus on analytical and normative legal philosophy as applied to income tax law, examining judicial reasoning in income tax cases. Seminars will examine such questions as: do legal philosophers’ expositions of the nature of law adequately explain the nature of income tax law? What light do theories of jurisprudence that have not traditionally examined income tax law shed on this question? What is the relationship between law and morality in the context of income tax? Contributions are welcome on all topics of taxation law. (Discussion will generally not be concerned with broad topics of fiscal policy, or, for instance, on whether governments should use taxes to redistribute wealth.)"
That's an unusual set of questions and I look forward to seeing the papers.  The other conference is to be held in Melbourne on Thursday and Friday July 19-20, 2012, and is entitled Defining, Taxing and Regulating Not-for-Profits in the 21st Century.  This is a very timely topic in the U.S. and, it seems, in a lot of other places too.  Here is the conference abstract:
The aim of the conference is to enable academics and other experts to reflect, from theoretical and comparative perspectives, on the theme of defining, taxing and regulating the not-for-profit sector. The conference coincides with a very active period of not-for-profit law reform in Australia, with the establishment of a new national regulator, the statutory definition of charity and other changes to the taxation and regulation of charities and other not-for-profit entities.
The conference features an international cast of characters and should provide a very welcome addition to the comparative tax literature.  Thank John P for bringing these to my attention!

Sunday, April 15, 2012

Tax protestors alive and well and living in Canada

The tax protestor movement is alive and well in Canada and getting some publicity just in time to serve as a warning to Canadian taxpayers readying their annual returns.*   I read with interest the recent case of Russell Porisky and his wife Elaine Gould, who ran a tax evasion counseling scheme out of B.C. for many years.  It seems Porisky cooked up a "natural person" argument about how Canada could not tax people acting in the capacity of natural persons, but could only tax them if they acted (presumably out of fear or ignorance) as legal persons.   Gould went along with Porisky to her detriment; both have been convicted and I believe still await sentencing.  The arguments, like those used by the darlings of the U.S tax protestor movement (led by the great Irwin Schiff, currently serving a 13 year sentence for his part in the ongoing saga), are completely nonsensical as well as spurious but make for good theatre.  

Check out this exchange documented by the judge in the case:
At the close of the Crown’s case I asked Mr. Porisky and Ms. Gould whether they wished to call any evidence.  Mr. Porisky said he could not make that decision unless he understood whether he was to give evidence in his “inherent personality as a natural person with no intent to profit”.  He wanted to tell the truth in the stand but the capacity he was to testify in would make a difference to his evidence.  A few minutes later in the dialogue he said 
I need to know if I make the decision to get into the stand, from which perspective can I speak?  Like therefore I need to know, in the eyes of the law, if one man is two persons, the natural or the legal, okay, which one can I speak as, or does it matter -- am I have the liberty to speak the truth and qualify it so I can speak to everything?  Because what it -- they have commingled a lot of stuff, and for me to properly address it, I'm going to have to be able to speak to everything to properly address it. 
And later:
Again, I feel like I'm being railroaded because I'm asking for clear answers.  I came here with a full intention on defending my -- my rights and -- and not having things being converted into something they're not, and I don't know how to do that if nobody's going to give me a straight answer.  I thought Crown had a duty -- I read their web page and they talk about honour and integrity, and now I'm been led one thing -- and for me to speak to everything, I'm going to need to be able to speak to it from my starting point of my existence. 
I didn't make it up.  Sir John Salmond I think is a highly respected man.  The Supreme Court relies on him.  I didn't make it up that one man's two persons in the eyes of the law.  And so from that perspective, I need -- that's why I tried to be as honourable and as open in the development of this, so that I could speak the truth and the whole truth from the proper perspective, so it does not get misconstrued or mislabelled or presumed to be something it's not.  And that's what I need to know.  If I make the decision and I go in that box, which person, in the eyes of the law am I? 
THE COURT:  You are Mr. Porisky. 
THE ACCUSED PORISKY:  Am I Russell Anthony Porisky in my inherent personality as a natural person, or am I a sovereign-granted personality? 
THE COURT:  You're Russell Porisky. 
THE ACCUSED PORISKY:  That's fairly misleading because that's not clear enough for me, Your Honour. …. 
THE COURT:  … Let's assume you get into the stand… and the Crown asks you, "What did you have for breakfast today?" Would it make a difference as to what capacity you were in? 
THE ACCUSED PORISKY:  For me, it would, Your Honour, yes.
Priceless.   The Court concludes, as it really must, that
"Mr. Porisky’s theory not only does not bear any legal logic but it also fails to accord with common sense.  It is a failed attempt at word magic and has no validity."
Tax protestors and dupes thereof, you've been duly warned.

In a similar case, a Manitoba chiropractor and tax protestor named Rosalie Chobotar was recently sentenced to six months in jail plus a fine of $162,513 for failing to pay her taxes from 2002 to 2007--she signed all her returns with "to the best of my knowledge without understanding."  That's rich!  And so, apparently, was she.  Chobotar seems to have been a “zero income” return filer—someone who filed annually but simply put zero on all of the lines, which she may have learned through the infamous work of Irwin Schiff.  His fraud on the public still lives on at paynoincometax.com even though the man himself is out of commission until 2016.  I do not advise calling the toll-free number for more information.

Note that both Porinsky and Chobotar defended themselves in court.  You know what they say about the clients of lawyers who defend themselves.  Chobotar actually absconded, apparently by physically leaving the court mid-trial, saying the court or Revenue Canada or both had no jurisdiction over her.  Again, good theater!  But bad outcome.  Lawyers who don't stick around to present their case don't usually win.

* Americans have until this Tuesday to file but north of the border they have until April 30.

"Geithner made me do it"--The viral nature of cheating on your taxes

If you see your neighbor cheat and prosper, you will be more likely to try to follow suit, says Dan Ariely, based on an experiment he conducted in which the test subjects were exposed to blatant cheating and adjusted their behavior accordingly.  He points to the Tim Geithner case as an example of widespread public exposure to blatant cheating--Geithner clearly got away with tax evasion and taught the public a lesson that it's ok to cheat since if you get caught, you just pay up, no harm, no foul.

Ariely says his study shows:
"Seeing someone cheat for their own benefit and then get away with it clearly has an impact on our moral behavior—loosening it to a substantial degree.

So, what does this experiment means for paying taxes? It means that the more we see politicians—the people who make our laws—fudge their taxes (which seems to happen continually), the more likely the rest of us are to adjust our understanding of what is right and wrong about paying our taxes, and do the same."
But, he says, there is hope if you can psychologically distance the test subjects from the cheater: "if we don’t think that we belong to the same social group we might not feel more justified in our own moral indiscretions, and instead be extra careful not to be confused with this other, not so moral, social group."

He concludes that we just need to not identify with our cheating politicians, in order to avoid acting like them.   That's going to be tough since identifying with "us" is what politicians typically have to do to be politically successful.

Thursday, April 12, 2012

Controlling policy debate on trade & development

UNCTAD has issued a letter decrying attempts by the OECD to silence it as a voice in the international economic development debate:

"Since its establishment almost 50 years ago at the instigation of developing countries, UNCTAD has always been a thorn in the flesh of economic orthodoxy.  Its analyses of global macro-economic issues from a development perspective have regularly provided an alternative view to that offered by the World Bank and the IMF controlled by the west.
Now efforts are afoot to silence that voice.  It might be understandable if this analysis was being eliminated because it duplicated the work and views of other international organizations, but the opposite is the case - a few countries want to suppress any dissent with the prevailing orthodoxy. 
...At time when pluralism is finally being meaningfully discussed in the election of the  President of the World Bank, it is ironic that OECD countries are endeavouring to stifle  freedom of speech within another multilateral organization."

The letter is signed by a long list of people, including Dani Rodrik.  The Tax Justice Network posted the letter along with this disturbing addendum:
John Burley, who worked for UNCTAD for many years in senior positions, and who coordinated the letter, gave a presentation in Geneva in which he provided some background information (supplemented with a couple of comments in an email):

"An attempt is going to be made there, on the basis of what we hear ... at the moment, to change UNCTAD's mandate by denying the organisation the right to continue – and I emphasise: to continue – to analyse and report on global macroeconomic issues, including the role of global finance in development.
. . . This is not a matter of money: it is an attempt to dilute the mandate of UNCTAD to work on macro-economic and global finance issues."
... Why is the UNCTAD message so unwelcome? The fact that UNCTAD has no formal responsibility for the global management of the international economy and none of its own funds to dispense means that its analysis is free of vested interests. ... 
... And it is precisely in its analysis of interdependence that UNCTAD brings added value to an understanding of how the functioning of the global economy impacts on the majority of the world's population who live in developing countries. Given the current pressure on the organisation and its secretariat, that contribution could now be gone for good (our emphasis).
. .
The developed countries in Geneva have seized the occasion to stifle UNCTAD's capacity to think outside the box. This is neither a cost-saving measure nor an attempt to "eliminate duplication" as some would claim."
This is not about tax policy per se though quite clearly tax policy is a major part of trade-based development initiatives.  So it is worth connecting this to the OECD's control of rhetoric over international tax.  The OECD likes to call itself a "market leader in tax policy," a self-assessment I often refer to as an understatement because there is not much competition in this market, if any, and the OECD seems to work rather diligently to ensure that remains the case.  India's response to the OECD's position on transfer pricing is a current example, as TJN notes in their post; they also point us to this guest post by David Spencer that outlines the ongoing tension between the OECD and UN tax committees.

There are high barriers to entry in the international tax policymaking market--you've got to have the right infrastructure and resources so you can hold conferences in attractive locations and get important people to show up and network together, and you need to be able to display some indication of your ability to influence national legislatures to adopt norms you develop.  The institutions that can do that, like the OECD, can only keep doing that so long as people don't start to think they fail to represent consensus, sufficiently to erode the influence of their ideas in political discourse.  As we know, high barriers to entry are good for the established monopoly, and the case seems no less true for the production of ideas, judging by the many efforts to eliminate competition.


10 Biggest U.S. Corporations: 1812 vs 2012


In 1812, they were mostly banks:
  1. Bank of the United States
  2. Bank of America
  3. State Bank
  4. Bank of Pennsylvania
  5. City Bank of New York
  6. Farmers Bank of Virginia
  7. Philadelphia Bank
  8. Manhattan Company
  9. American Fur Company
  10. Boston Bank
NPR has the story.  Of these, the Bank of America is still hanging in there, 200 years later--here is the list for 2011 from Forbes:

  1. Wal-Mart Stores
  2. Exxon Mobil
  3. Chevron
  4. ConocoPhillips
  5. Fannie Mae
  6. General Electric
  7. Berkshire Hathaway
  8. General Motors
  9. Bank of America
  10. Ford Motor

Of these, three were bailed out in 2009-2010: Fannie Mae ($400 billion), General Motors ($50 billion), and ...wait for it...Bank of America (about $120 billion).

In 2012, which of these will be off the top ten list?


The Lobbyists are Winning: Corporate Tax Transparency edition

The activist-led movement to increase multinational tax disclosure is proving to be a full-employment program for natural resource industry lobbyists.  The money and energy available for fighting against transparency seems limitless.  We have seen the effects of this in the US, where Dodd-Frank's section on extractive industry transparency has been completely undermined and consistently sidelined as a result of lobbyists.  We have seen the effects in Canada, where the industry managed to kill transparency legislation all together by means of a tidal wave of lobbying by the energy industry there.  Today the FT tells a similar tale unfolding in the EU.

There is a perhaps not obvious but very pernicious undercurrent in this transparency contest.  It is that in each country, lobbyists are using the success of the lobbyists in the other countries to bolster the cause for their own success.  No matter we may like to think about the nature of tax policy as somehow a sacred and protected space for purely national politics, that hallowed chamber of sovereign entitlement, it's clear that lobbying is fully globalized and therefore tax policy is, too.

Today's FT story provides a case in point.  First, the FT notes that the EU's work on transparency was prompted by the inclusion of new corporate tax information disclosure standards for resource extractors (think oil, gas, etc):

The European Commission last year proposed a scheme that allowed for payments for specific projects to be tracked, with reporting requirements that broadly matched the US approach enacted in the Dodd-Frank Act.
Just by putting the possibility of corporate tax transparency into legislation, even though it could not and still cannot be implemented without further action through federal regulations, Dodd-Frank put extractive industries transparency on the map of legislative possibilities, and therefore cleared some space for the policy to spread to other nations (I analyze this more thoroughly in my forthcoming book chapter on global tax activism).

The FT reports that industry in the EU responded by protesting the new rules as unnecessary, onerous, etc.--in other words, a set of self-serving arguments with which those of us who have been following this issue in the US and Canada have become all too familiar and most of which do not hold up under scrutiny.  But lobbying works very well, and so the EU is considering a much less transformative version of the proposal, one that would not require very much disclosure if any at all.

The FT closes the circle by concluding that:

If the compromise passes in Brussels, it will bolster industry arguments that the US rules being drawn up to implement Dodd-Frank should be watered down to match the EU approach and ensure a level playing field.
The idea that tax policy is in any sense a purely national project could not be more clearly debunked.  The EU's imminent adoption of a more lax standard arms lobbyists in the US with a fresh round of anti-transparency ammunition.  Their ability to use this to further the anti-transparency cause in the US will in turn re-invigorate lobbying in Europe and elsewhere.  This will continue until transparency is uniformly killed, unless the pro-transparency lobby gains a similarly viral foothold from which to reinvigorate the campaign for transparency.  It is an international game with fascinating network aspects and effects.  Too bad then that in the meantime, a policy that really ought to be implemented, not least because it is in fact written into the rule of law here in the US at least, will be stalled indefinitely.

On a related note, it is worth recognizing that a new euphemism is emerging in international tax policy that is steadily gaining ground through casual and unexamined use.  That is the idea that this or that tax policy is necessary to "ensure a level playing field." Both sides of the transparency issue have used the term to support completely opposing goals in the past, so it would seem that the term means very little.  That means a translation is in order when people use the term to score political points.

Let us be clear then that when used by opponents of transparency, "ensuring a level playing field" is what people say when they mean that the lobbyists are winning.  That is because a level playing field would quite obviously exist when the market has full information--that is, when all multinational companies engage in full disclosure of their tax payments in all countries, and all stakeholders--shareholders, taxpayers, governments, and watchdog groups--have the same information about how generous tax policies support industry all over the world (this is how the pro-transparency crown use the term).  When what is sought is a market with little or preferably no publicity of this kind of information, "the level playing field" means something very close to the current status quo--the product of all that successful lobbying to date.

Wednesday, April 11, 2012

Water: a Public Good?

Is water a public good?  Privatizing water has led to all kinds of traumatic consequences in poor countries, with many complaints aimed at IMF conditionality-imposed schemes.  India is considering a draft bill to privatize water there, where shortage seems particularly imminent: "India has more than 17 percent of the world's population, but has only 4% of world's renewable water resources with 2.6% of world's land area."  There is plenty of worry about what the bill will mean in terms of pricing for profit-oriented industry and long-term infrastructural consequences.  In a post last month I suggested that I thought waste disposal likely ought to be a public good because a private market would tend to want more garbage (more volume, more profit), while a public system might try to minimize garbage in order to reduce costs or meet other social goals such as conservation--the same principle seems to hold for water.

Visual News has a story (and of course a great infographic) on America's water crisis:


Basically we consume too much, both directly and indirectly, we waste a lot due to aging infrastructure, and we otherwise contaminate it with chemicals.  A startling stat: municipal water in 71% of U.S. cities has too much hexavalent chromium in it. If you don't remember why you should worry about that, you just need to think Julia Roberts:


Here is the CIA World Factbook's page on water resources, showing " the long-term average water availability for a country in cubic kilometers," i.e., the total water available to the country in an average year.

The 10 countries with the most water on average:
  1. Brazil--8,233 cu km
  2. Russia--4,498 cu km
  3. Canada--3,300 cu km
  4. United States--3,069 cu km
  5. Indonesia--2,838 cu km
  6. China--2,830 cu km
  7. Colombia--2,132 cu km
  8. Peru--1,913 cu km
  9. India--1,908 cu km
  10. Venezuela--1,233 cu km


And the 10 countries with the least:
  1. Kuwait--0.02 cu km
  2. Saint Kitts and Nevis--0.02 cu km
  3. Maldives--0.03 cu km
  4. Malta--0.07 cu km
  5. Bahrain--0.1 cu km
  6. Qatar--0.1 cu km
  7. Antigua and Barbuda--0.1 cu km
  8. Barbados--0.1 cu km
  9. United Arab Emirates--0.2 cu km
  10. Cape Verde--0.3 cu km